Showing posts with label wiggle room. Show all posts

Thursday, December 23, 2010

Financial Goals for 2011

In my most recent post, I shared that I'd been organizing my finances (reconciling savings plans, debt reduction plans and budgets). Naturally, the next thing for me to do was to think about what my goals are for the upcoming year and what I need to do to make sure these goals are achieved. Below, you will find my goals and the steps I intend to take to make them a reality:
  • Zero credit card balance: My goal is to end every credit card billing cycle without a balance. This is one way to ensure that I don't spend above my income. I can make regular purchases, such as gasoline and groceries, with my credit card. In fact, I've been considering a rewards card to earn points for ___________ (<<that means I don't know, yet >). This year, I paid $68.21 in interest charges.  That's enough money for gas (and then some), a nice dinner with my boyfriend, an outfit, or a small contribution to my savings plan (after all, it all adds up!).
  • Max out my Roth IRA: You already know that I've been kind of obsessed about paying off my car note. As such, I don't have much money left over to max out my IRA. With a projected payoff date of April 28, 2011, I have May 2011 through April 15, 2012 to contribute $5,000 to my individual retirement account. What do I have to do to make this happen? Contribute $454.55 each month to the account. With two "extra" paychecks in 2011, I may have the flexibility to reduce the monthly amount, but this requires that I'm diligent about redirecting a sufficient amount of those checks to the IRA. Knowing me, I'd like to set a few bucks aside for fun =)
  • Pay off my car note: Originally, I planned to pay off my car note by June 2012, that is, until I ran the numbers on my beau's proposition of significantly increasing the principal payment amount. Currently, I am on track to achieve this goal by the end of April 2011, especially if my assumptions about my anticipated tax refund are correct. If they are less than I estimate, I may have to postpone the due date for this goal (which, undoubtedly will effect the savings goals). Let's keep our fingers crossed and hope I am at least right :)
  • Generate at least $250/ month in extra revenue: Before I took the job that I currently hold, I had a steady goal of generating $3,000 in net income each month. With my deductions for my defined contribution plan, I am short of this goal by $222 each month. For the past few years, I've been toying around with a business idea that promotes personal finance. My goal for next year is to get serious about a web design and marketing plan so I can realize some income. $250/month of income to be exact. To be clear, I'm not looking to pocket all income; undoubtedly, I will reinvest into the business, but having the income will definitely provide some peace of mind.
  • Accumlate $10,000 in non-retirement savings accounts by 05/31/2012: These funds would be available for immediate access and as part of my emergency savings. Why $10,000? Frankly, it's an arbitrary amount, but it's definitely a "stretch goal." There are a number of factors at play. Let's start with the not so good possibilities: what if I don't pay off my car by the end of April? What if I don't generate enough additional income? Well, my $10K goal within 12 months will be postponed (by the way, I'd redirect my "car payment" money to this goal). For me to achieve this goal, I need to set aside $833.34/month.  
If you recall, I have $1255 available as discretionary money each month. I'm comfortable spending $200 of this amount for fun stuff. So $1055 - $454.55 (Roth)-$833.34($10K goal)= $-232.89. A girl MUST increase her income to make these goals come true. Even if I sacrificed fun stuff every month (i.e. the previously mentioned $200/month), I'd still be a few bucks short! 

At any rate, these are my financial goals for 2011. What are your financial goals for 2011, if any? How do you intend to achieve them?

Tuesday, December 7, 2010

This Way or That?

The very nature of my blog highlights the point that there are often a multitude of ways to achieve one's financial goals. I wish I could say that the motivation for today's post is purely financial, but it's not. Nevertheless, there are many applications of the concept of achieving a task in a variety of ways. For example, you have read my many posts about paying down my car note. Initially, my goal was to eliminate my car note by June 2012 by making monthly principal only payments of $230.89. My boyfriend, who paid off his $30,000+ vehicle loan early, recommended that I see what areas of my budget I could make adjustments to in order to add more to this additional payment. After number crunching with loan amortization tables and a variety of savings projections, I settled on $1245/month to pay the car note (this amount includes the original $269.11 payment), this amount later became $1045/month as a I soon realized that twelve hundred bucks a month left me with no wiggle room.

I've also thought about the variety of advice/information promulgated about:

Investing: asset allocations based on age, how to pick a stock, what indicators to assess when selecting a fund, how much to save for retirement, tax diversification...

Saving and debt management: what debts to pay first, saving a set dollar amount or a percentage of income, what type of savings instrument to use, how much to set aside for emergencies....

Insurance: how much coverage, term or whole life, who to list as a beneficiary or beneficiaries...

The list goes on and on. I can only imagine that as my income increases and my options within financial planning expand that this list will grow even larger! However, I am comfortable knowing that - despite how overwhelming it may seem- I am constantly learning about and taking control of my finances. Regardless of the recommendations, I am ultimately responsible for the consequences of my decisions: to save one way or another, to pick a stock or bond fund because of a certain indicator, or whatever the case may be.

Have you ever received advice about the way you should handle your finances? Was it solicited or unsolicited? Was it more helpful or harmful?

Tuesday, November 30, 2010

Funky Credit Card Action

Last week Wednesday, I received a recorded voice message advising that I call Capital One because fraud had been detected on my account. When I checked the message, I was getting ready to take a nap, but nothing makes your mind wander -and interrupt your ability to rest peacefully- more than a financial woe. So I postponed nap time and called back. It's still not clear to me how and why my account was flagged, but as a precaution, I was asked to verify several recent purchases and to agree to a new account number and card. Fine. What wasn't so fine was that Thanksgiving was a day away, I was at the very end of a pay period and I was asked to make some unexpected purchases (bundt cake pan, anyone?)

Ordinarily, I would have made such purchases using my credit card, but that sucker was out of business. With just over nine bucks in my checking account, I transferred $50 from my savings account so I could go shopping. Luckily, the total of the items I purchased came under $50, so I transferred the remainder back to my savings account (after my direct deposit cleared, of course).

These events made me wonder....should I keep a buffer of $100 in my checking account (or some other amount; frankly, $100 is an arbitrary amount). In doing so, I wouldn't have to use my credit card to make purchases [and dip into funds set aside in subsequent pay periods/spending plans].

Do you have a cushion or buffer amount in your checking account? Or do you access funds from your savings account as needed? Have you ever experienced fraud on a credit card account?

Monday, October 25, 2010

7 Days and 1,604.85 Dollars Later...

Last week, I posted "Decisions, decisions, decisions..." to reflect the conundrum du jour: should I use my "extra" paycheck for a trip to Houston or do other stuff with it?

Well, it took me less than a week to blow through more than my "extra" check. Here's how I did it:
  • $717.73 for bills ($689.01 for my car payment and $28.72 to pay off my credit card balance)
  • $255.64 for "other" or miscellaneous expenses (stamps, airfare, brake lights (the DIY replacement of $6.35 is much less than the $29.99 the rotor-replacers wanted to charge...more on them, next), pet food, public transportation fare).
  • $250.10 (on a credit card) for an unexpected car repair.
    • I had my coupon ready to go for my oil change, but after a road test (something that I insisted be done because I've been hearing squeaking while braking), I was informed that my front brake rotors needed to be replaced. Unfortunately, they were worn down to the point that resurfacing them (a cheaper alternative to rotor replacement) was not a feasible alternative.
  • $197.63 for food (sadly, more than half of this was spent on eating out, including this little indulgence).
  • $71.43 for gasoline.
  • $60 for an ATM withdrawal ($49.72 was spent on a day trip to NYC - tolls and food- and state park admission for a "hiking" trip in a part of the Appalachian Mountain range. I spent another $6 as a tip for lunch that I didn't pay for.) Sadly, I can't account for the outstanding $4.28.
  • $39.53 for savings (I wanted to make the amount in my ING Direct account an even number. Lame. I know).
  • $12.79 for a bottle of vino (yes, liquor has it's own category in my spending plan). Don't judge me ;)
All said and done, I will have $34.26 left over from this "extra" check. None of which, I might add, went towards a trip to Houston. I should mention, however, that part of the airfare cost listed in the miscellaneous category includes a membership fee for Spirit Airline's "$9 Fare Club." This service, at approximately $60, will pay for itself over the purchase of two airline tickets (one down, one more to go) as I will receive special fares for being a member ($19 one way ticket to travel 900+ miles, anyone?)

I know this isn't the most impressive record of spending "fun" money, but tell me, WHAT WOULD YOU HAVE DONE?

I guess I don't have "money to blow".....

 
From Candy Slice Comedy

Thursday, September 16, 2010

It's My Budget! Part 2 of 3


Earlier this week, I shared my budget and categories of spending that were non-negotiable.

Today we will cover the part of my budget where I have a little flexibility: meet my “maybe negotiable” expenses.


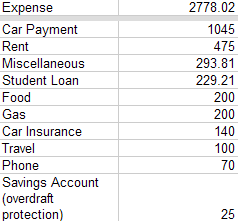
I spend $565 in “maybe negotiable” categories each month. Here they are:

Food, $200: While I’ve never been one to order out “every day of the week”, I do enjoy an occasional indulgence such as happy hour or a $7 slice of cake (Hey, don’t judge me! We both know that Cheesecake Factory has it going on!). I recently discovered that I could shave about $40 off of my food expenses if I remained diligent about packing my lunch and not eating out “so much” (ex. twice a week). When it comes to grocery shopping, I make a list based on what’s in the sale circular. I haven’t been a super-duper-coupon-clipping-lady when it comes to food shopping, so there might be an opportunity here. By the way, I can get down like Cookie Monster...


Gas, $200: Currently, carpooling and public transit are not feasible options for my day-to-day travel because: a) my job requires that I have my own transportation (luckily, I don’t have to travel out of the office everyday; but when I do, I am reimbursed for it), and b) although I live 40 miles away from the J-O-B, there is no direct route (via mass transit) from where I am to where I need to be. I’d have to drive at least three-quarters of the way or take fifty million transfers to get to work (okay, so 50,000,000 transfers is a bit of an exaggeration).


Car Insurance: $140: I could pay the entire premium out of my savings (and eliminate the inconvenient “convenience fee” tacked on for monthly payments), break my premium into larger chunks (ex. pay it over the course of 2 or 3 months vs. monthly), or do what I’m doing (pay in monthly installments and spend $25 over the course of 5 months to pay the entire amount. I should mention that 1/6 of my car insurance premium is less than $140 I currently pay; at the rate I’m going, I’ll pay the entire premium in less than 6 months.


Savings Account, $25: Not too long ago, I was familiar with overdraft fees in a way that’s embarrassing to admit to. In order to mitigate this issue, I signed up for overdraft protection with my primary bank. To avoid monthly maintenance fees on the savings account where the overdraft service pulls from, I have to maintain a monthly deposit of at least $25. Staying on top of my account balances and outstanding transactions has resulted in ZERO overdraft fees for me (YAY!). In fact, the last time I incurred such a fee was April 2009 ($245 of overdraft fees in that month alone; you better believe that I signed up for overdraft protection the following month. I was absolutely disgusted by my waste and irresponsibility!)