Showing posts with label car insurance. Show all posts

Thursday, December 30, 2010

One More Day of 2010

Image from: www.geeks.pirillo.com
Lately, I've been reflecting on this year and the past decade (technically, the past eleven years, but I digress). It never ceases to amaze me how quickly time "flies by." My sister warned me that "after 21, it's all a blur." Blur or no blur, I'd like to review some of my accomplishments and a few things I am looking forward to in the new year.
 
What I'm Proud of... 
  • Procuring a higher-paying position with an organization I admire and a wonderful group of colleagues. 
  • Making massive additional payments to eliminate my car loan debt.
  • Reining in credit card spending and managing the account so that I have a small balance (i.e. less than 30% of my credit line) or zero balance.
  • Sharing my financial experiences with the world [wide web].

What I'm Looking Forward to...
  • Increasing my savings and investing amounts (including maxing out IRA and getting on track to save $10,000).
  • Increasing my net income.
  • Finally eliminating my car note...and increasing my principal payments to my student loan debt.
  • Consistently paying my credit card balance in full.
  • Expanding my knowledge about insurance, taxes and investing.
What was YOUR biggest financial accomplishment of 2010?

P.S. HAPPY NEW YEAR!!! Have fun and be safe!

Tuesday, November 23, 2010

Set it Right or Else...

The title of this post refers to your perspective. Two posts ago, I shared that my money fear boiled down to being financially unstable and restricted by debt. Well here's a quick update about my "mini-dilemma." The car repair wasn't some irrational amount of money. After my coupon, I paid $231.66. No more "service engine light" and no more "gettin' jiggy with it" action from my engine.

Now about my perspective...
I'm not the type of person to spend my resources recklessly then look to someone else come to my rescue. But I do know, for sure, that if I legitimately faced an issue that cost me more than I have in all of my bank and investment accounts and more than my credit card limit, I still have somewhere to turn: family and friends. I know they would come to the rescue because they have in the past. For example:
  • I'd worked through most of my undergraduate studies to pay for rent and tuition (whatever scholarships and loans didn't cover). It wasn't until my senior year that I focused my efforts on saving up to purchase a car. What I'd saved wasn't enough to purchase a reliable car on my own. And heading into grad school with a $1300 monthly stipend spoke volumes about my capacity to re-pay a car loan (that is to say, it wasn't in the budget!). You might argue that I didn't "have" to purchase a car, but I was headed to a place where I had no networks and there was little (read: absent) public transportation. In short, I was forced to purchase a car. Who dropped some stacks to fill the gap? Dad.
  • After opening a Maaco credit card and spending $2500 of my own money to repair my car after an accident, my mom fronted me several thousand dollars to use for a down payment on another car. Unfortunately, when I retrieved my car from the body shop, the engine seized. Estimated replacement cost: $5600 for a rebuilt engine. I paid about that much for the car. And considering that I had JUST gotten out of the repair shop, it didn't seem prudent to drop that kind of money on it. So I got another car, with the help of Mom.
  • The car I purchased (with help from mom) was stolen. Everyone knows that when you file an insurance claim, you have to pay a deductible for services rendered by/through your insurer. At the time, my deductible was $1000 (it was this high because I wanted to pay lower premiums). However, stupid me didn't have the full $1000 in liquid savings. I would've been forced to pull funds from my investment accounts (which would suck: fees and penalties and crap) had it not been for my boyfriend. He surprised me and put a check in the mail. As it turns out, I didn't have to pay the deductible because of the way my appraisal turned out, but he was there for me nonetheless.

Going forward, I should be reminded of these instances - and many more- of support around me and not freak out (as much :>) when I'm faced with a financial "dilemma."

Who would you turn to if you exhausted your resources in case of emergency/major unexpected expense?

Tuesday, November 2, 2010

Dumb Marketers or Dumber Consumers?

Since when did spending money equate to saving money? After plopping down on the couch for some good ole tube watching time, I couldn't help but realize how many companies were trying to appeal to my desire to save money. Here's the thing: they got it all wrong. Instead of asking me to change my car insurance provider to "save" hundreds of dollars, how about you offer coverage at no cost so I can use the money for an upcoming vacation? Rather than tell me I can get a ton of features from your cable/telephone/internet service for only $99/month - a "bargain" compared to competitors - cut me a check to deposit into my emergency savings account.

I've always believed that saving money was about setting money aside for future use, whether it was for a vacation, unexpected expenses or having 'enough' to comfortably use for investing (i.e. secure an amount of money I wouldn't mind "losing"; not that that's the intention, but I digress). Some may argue that saving is about, or also includes, reducing one's expenditures. Well, help me understand this...what good is the amount of money you didn't spend if you don't set it aside (i.e. save it)? Most folks spend their "savings" on other expenses. Here's a great example: you go to the grocery store and when you check out, you learn that because a number of items were discounted and you used coupons, you "saved" $25. What do you do with that $25? Do you think, "Gee, I was intending to spend $75 to purchase these items, but only spent $50, let me set aside the remainder of what I budgeted" or do you say "great, now I can go to happy hour!"?

I could care less about what you do with the money you did not spend because of reduced prices, but I am encouraging you to be clear about what saving money is. And if you're not setting the bucks aside for future use, whatever that use may be, and particularly in a savings vehicle (piggy bank, anyone?), then I'm afraid to tell you that you're simply spending less. Kudos for finding a bargain ;)

Thursday, September 16, 2010

It's My Budget! Part 2 of 3


Earlier this week, I shared my budget and categories of spending that were non-negotiable.

Today we will cover the part of my budget where I have a little flexibility: meet my “maybe negotiable” expenses.


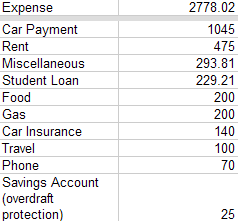
I spend $565 in “maybe negotiable” categories each month. Here they are:

Food, $200: While I’ve never been one to order out “every day of the week”, I do enjoy an occasional indulgence such as happy hour or a $7 slice of cake (Hey, don’t judge me! We both know that Cheesecake Factory has it going on!). I recently discovered that I could shave about $40 off of my food expenses if I remained diligent about packing my lunch and not eating out “so much” (ex. twice a week). When it comes to grocery shopping, I make a list based on what’s in the sale circular. I haven’t been a super-duper-coupon-clipping-lady when it comes to food shopping, so there might be an opportunity here. By the way, I can get down like Cookie Monster...


Gas, $200: Currently, carpooling and public transit are not feasible options for my day-to-day travel because: a) my job requires that I have my own transportation (luckily, I don’t have to travel out of the office everyday; but when I do, I am reimbursed for it), and b) although I live 40 miles away from the J-O-B, there is no direct route (via mass transit) from where I am to where I need to be. I’d have to drive at least three-quarters of the way or take fifty million transfers to get to work (okay, so 50,000,000 transfers is a bit of an exaggeration).


Car Insurance: $140: I could pay the entire premium out of my savings (and eliminate the inconvenient “convenience fee” tacked on for monthly payments), break my premium into larger chunks (ex. pay it over the course of 2 or 3 months vs. monthly), or do what I’m doing (pay in monthly installments and spend $25 over the course of 5 months to pay the entire amount. I should mention that 1/6 of my car insurance premium is less than $140 I currently pay; at the rate I’m going, I’ll pay the entire premium in less than 6 months.


Savings Account, $25: Not too long ago, I was familiar with overdraft fees in a way that’s embarrassing to admit to. In order to mitigate this issue, I signed up for overdraft protection with my primary bank. To avoid monthly maintenance fees on the savings account where the overdraft service pulls from, I have to maintain a monthly deposit of at least $25. Staying on top of my account balances and outstanding transactions has resulted in ZERO overdraft fees for me (YAY!). In fact, the last time I incurred such a fee was April 2009 ($245 of overdraft fees in that month alone; you better believe that I signed up for overdraft protection the following month. I was absolutely disgusted by my waste and irresponsibility!)