Showing posts with label gas. Show all posts

Thursday, June 16, 2011

Trouble Staying Focused

I'm still sick and continue to struggle with my spelling, as I shared earlier this week. Nevertheless, I will do my best to think through my drug/sick-induced brain to share with you what has been going on.

My spending for the last two months has been kind of "free spirited". I've purchased breakfast nearly every day (Monday through Friday), eaten out almost as much for lunch, and had more take out for dinner than usual. Additionally, I've spent quite a bit of time entertaining friends from out of town or going out of town to be entertained by friends (yeah, yeah, I know, gasoline is extra stupid expensive). These things don't pay for themselves and unfortunately, many of these expenses were not part of my regular budget. So what did I do? I used money I set aside for my super duper car payments. Or, I used my credit card....and then used money from my super duper car payment to pay off the credit card balance.

I'm all for the "life is short, so you gotta have fun." Yet, sometimes, I find myself struggling to balance it all. Surely, additional income would help me "have it all", so to speak. What's most important, however, is that I develop a firmer sense of discipline to remain on track with my goals, while having a little bit of fun, as well :)

My boyfriend has a similar goal of paying off a debt sooner than later. He has diligently set aside $2,000 a month to get rid of a second mortgage on his first property. He has faced similar temptations of spending money in other places (heck, I'm likely the source for half of such temptations); in spite of them, he's on track to get rid of his loan by the end of August (congrats in advance, babe ;>).

Me? I'm repeating the same old sorry song about pushing back "the date". I haven't thought at length about what it means to pay off this debt ASAP. "I know" that it will mean I can save a super amount every month (for my $10K goal). "I know" that it will mean that I can have a chunk of disposable income to do whatever I want with (shopping and weekend trips to California have been among my latest obsessions). However, I'm not connecting what "I know" with what I should be doing. Side note: I love to see how behavioral economics shows itself in my life :).

Nevertheless, I will continue reminding myself of why I set out on this particular journey and continue to work towards my goals....in spite of many "distractions."

What do you do when you lose focus? What helps you get back on track?

Tuesday, December 21, 2010

Budgets, Holiday Stuff and Revisiting Financial Goals

...and I'm back! I sincerely apologize for being absent last week, but I'm back now =)

So, what's been going on? The usual, the not-so-usual and some more of the usual. Let's get started with the usual.

The Usual
I've been diligently tracking my expenses in my tracker housed on Google Docs. I've exceeded my allocated amount for food and car expenses: footing the bill for my sister's birthday dinner; being a bit impulsive (eating out, mostly); increasing gas prices (is anyone else paying around $3/gallon?); and regular car maintenance (the coupon for my oil change this time around wasn't $19.99 + tax :<).

The Unusual
Holiday stuff. You know, buying gifts and bringing in whatever you signed up for for the holiday party at work. Actually, the work stuff was easy. We had a cookie swap and I brought a non-cookie item to swap: brownies. Had I not been distracted by the massive amounts of sugar tempting my waistline, I would've repackaged the cookies and sold them for income =) The not so easy stuff is holiday shopping. To cover the expense of Christmas gifts without regretting it in January (i.e. financing all purchases with my credit card with no clear way of paying it off), I decided to decrease the amount of my car payment this month to $356.98 (I know, it's a weird amount). At any rate, doing so allowed me to spend $705 of "car payment" money on gifts for my parents, sisters, boyfriend, best friend and godson. Sadly, I've spent $690 and some change and I still have a few items to pick up. Fortunately, I have a few bucks in my "immediate access" savings account (this is NOT my emergency savings account) that I'm comfortable using to cover these items.

More of the Usual
Revisiting goals and planning. I spent quite a bit of time today updating my savings plan [another Google spreadsheet I use to track the balances of my savings account linked to my checking account (see "immediate  access" savings account above), my ING Direct account (emergency savings), my Roth IRA, regular brokerage account and 403(b)] and reconciling it with my 2011 budget. It feels SO DARN GOOD to account for every single penny. Did you get that? EVERY. SINGLE. PENNY. I know where it came from or where it went and for what purpose. Moments like these help me feel in control of my finances, and not vice versa...something that I occasionally freak out about. Nevertheless, I am on track to enjoy my boyfriend's birthday (I've planned a surprise trip for him), my girlfriend's birthday (we're going to be "Bahama Mamas"), a winter weekend getaway in the Poconos with a gaggle of friends, my 2nd year anniversary with the beau, paying off my car note, and my friend's wedding. And all of these things are happening in the first half of the year! To be fair, I am making assumptions about my anticipated tax refund, the bulk of which will go towards principal reduction on the note. Everything else is accounted for (i.e. planned to come from my regular income).

As I prepare for 2011 (and the end of my car note, hooray!), I'm considering the opportunities to save more, invest more, and to be better equipped to pay for travel and entertainment expenses that inevitably have a habit of "popping up." My post later this week will focus on financial goals [and concomitant action plans] for 2011.

How have you been handling expenses related to the holiday season? Did you set up a budget? Are you "winging it?" Have you started to plan for 2011 financially? Have/will you do a "2010 Year in Review" for your finances?

Thursday, September 16, 2010

It's My Budget! Part 2 of 3


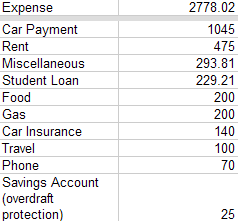
Earlier this week, I shared my budget and categories of spending that were non-negotiable.

Today we will cover the part of my budget where I have a little flexibility: meet my “maybe negotiable” expenses.


I spend $565 in “maybe negotiable” categories each month. Here they are:

Food, $200: While I’ve never been one to order out “every day of the week”, I do enjoy an occasional indulgence such as happy hour or a $7 slice of cake (Hey, don’t judge me! We both know that Cheesecake Factory has it going on!). I recently discovered that I could shave about $40 off of my food expenses if I remained diligent about packing my lunch and not eating out “so much” (ex. twice a week). When it comes to grocery shopping, I make a list based on what’s in the sale circular. I haven’t been a super-duper-coupon-clipping-lady when it comes to food shopping, so there might be an opportunity here. By the way, I can get down like Cookie Monster...


Gas, $200: Currently, carpooling and public transit are not feasible options for my day-to-day travel because: a) my job requires that I have my own transportation (luckily, I don’t have to travel out of the office everyday; but when I do, I am reimbursed for it), and b) although I live 40 miles away from the J-O-B, there is no direct route (via mass transit) from where I am to where I need to be. I’d have to drive at least three-quarters of the way or take fifty million transfers to get to work (okay, so 50,000,000 transfers is a bit of an exaggeration).


Car Insurance: $140: I could pay the entire premium out of my savings (and eliminate the inconvenient “convenience fee” tacked on for monthly payments), break my premium into larger chunks (ex. pay it over the course of 2 or 3 months vs. monthly), or do what I’m doing (pay in monthly installments and spend $25 over the course of 5 months to pay the entire amount. I should mention that 1/6 of my car insurance premium is less than $140 I currently pay; at the rate I’m going, I’ll pay the entire premium in less than 6 months.


Savings Account, $25: Not too long ago, I was familiar with overdraft fees in a way that’s embarrassing to admit to. In order to mitigate this issue, I signed up for overdraft protection with my primary bank. To avoid monthly maintenance fees on the savings account where the overdraft service pulls from, I have to maintain a monthly deposit of at least $25. Staying on top of my account balances and outstanding transactions has resulted in ZERO overdraft fees for me (YAY!). In fact, the last time I incurred such a fee was April 2009 ($245 of overdraft fees in that month alone; you better believe that I signed up for overdraft protection the following month. I was absolutely disgusted by my waste and irresponsibility!)