Showing posts with label negotiable expenses. Show all posts

Thursday, June 16, 2011

Trouble Staying Focused

I'm still sick and continue to struggle with my spelling, as I shared earlier this week. Nevertheless, I will do my best to think through my drug/sick-induced brain to share with you what has been going on.

My spending for the last two months has been kind of "free spirited". I've purchased breakfast nearly every day (Monday through Friday), eaten out almost as much for lunch, and had more take out for dinner than usual. Additionally, I've spent quite a bit of time entertaining friends from out of town or going out of town to be entertained by friends (yeah, yeah, I know, gasoline is extra stupid expensive). These things don't pay for themselves and unfortunately, many of these expenses were not part of my regular budget. So what did I do? I used money I set aside for my super duper car payments. Or, I used my credit card....and then used money from my super duper car payment to pay off the credit card balance.

I'm all for the "life is short, so you gotta have fun." Yet, sometimes, I find myself struggling to balance it all. Surely, additional income would help me "have it all", so to speak. What's most important, however, is that I develop a firmer sense of discipline to remain on track with my goals, while having a little bit of fun, as well :)

My boyfriend has a similar goal of paying off a debt sooner than later. He has diligently set aside $2,000 a month to get rid of a second mortgage on his first property. He has faced similar temptations of spending money in other places (heck, I'm likely the source for half of such temptations); in spite of them, he's on track to get rid of his loan by the end of August (congrats in advance, babe ;>).

Me? I'm repeating the same old sorry song about pushing back "the date". I haven't thought at length about what it means to pay off this debt ASAP. "I know" that it will mean I can save a super amount every month (for my $10K goal). "I know" that it will mean that I can have a chunk of disposable income to do whatever I want with (shopping and weekend trips to California have been among my latest obsessions). However, I'm not connecting what "I know" with what I should be doing. Side note: I love to see how behavioral economics shows itself in my life :).

Nevertheless, I will continue reminding myself of why I set out on this particular journey and continue to work towards my goals....in spite of many "distractions."

What do you do when you lose focus? What helps you get back on track?

Tuesday, March 15, 2011

Thank Goodness I'm Out of School!

If, like school, my attendance was recorded on this blog, I'd probably be failing. I haven't posted in two weeks! Which is especially terrible since I post twice a week. Nevertheless, I will share what I have been up to.....spending money recklessly and not so recklessly.

The reckless part comes into play because my financial decisions over the past two weeks have effectively set my car payoff date back by a month. A large part of this is because I spent $1,010.31 (I negotiated this down from the original quote) to get my tie-rod and rear struts replaced (this is the "not so reckless" part of my spending). The rest of my car payment money (and then some) was spent on spa services ($188), dinner ($55), hair supplies ($20 and change), airfare, eating out (including Dunkin Donuts), and a new pair of sneakers ($44), among other things. 

Why the splurge? Why the major deviation from "the plan"? Frankly, there's no excuse, yet, I found myself justifying expenses because it was my birthday. Yup. I turned 27 years old last week. And unlike previous birthday celebrations, I did not plan for this one. No trip out of town. No dinner with my beau. Nothing. It was quite depressing. I guess that saying about money not being able to buy you happiness is true....I sure made an attempt at it (enter sad face).
Image from murlocparliament.com

Now it's time to refocus and get back on track. No more emotional spending, no more failing to plan and trying to make up for it at the last minute.

Have you ever made emotional purchases? Splurged in an effort to "fill a hole?" What was the consequence?

Tuesday, September 21, 2010

It's My Budget! Part 3 of 3

In the last two posts, I shared my budget and categories of spending that were non-negotiable and maybe negotiable. Today we will cover the part of my budget where I have the most flexibility/options. 


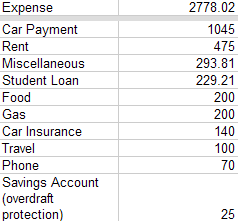
Every month, I will spend $293.81 for my most negotiable spending category: Miscellaneous!
The amount available for miscellaneous expenses has increased by $200 recently because of a change in my car payment ($1245 to $1045). What exactly qualifies as “miscellaneous”? Pet expenses (I have two furry friends** that require food and litter), storage rental (I’m hoping to lose this expense SOON; a little more about this later), entertainment, gifts, airfare to see my sweetheart and occasional car maintenance (think oil changes and car wash). **I wish my cats were as cool as these two...


Although I like to think that my budget in reality reflects exactly what’s on this spreadsheet, the sad truth is that I occasionally use my credit card to make purchases.....and I often don’t pay the balance in full every month (YIKES!) What’s not-so-sexy about this idea is that I know interest charges are lost opportunity costs. Having looked at my credit card statements for the past 8 billing cycles (starting since January 11, 2010), I’ve paid $59.11 in credit card interest. That’s enough money to fill up my gas tank and buy a decent lunch! Fortunately, the miscellaneous category of expenses also includes me taking a stab at whatever credit card balance exists, so it’s not an ever-growing ball of debt.


Now about that storage unit...
I’m working on getting a nice chunk of money from selling all of what I have (it’s mostly furniture), but I am more excited at the prospect of reclaiming $97 a month (bye-bye monthly storage payment; hello more money for saving, expenses, credit card balance elimination, etc.!). I’ve posted items for sale on Craigslist and received a few responses, but none that adhere to the requests of the post (Hey Craigslist customers! Please read the entire post before you start emailing sellers silly questions about what’s for sale. The information is already there! Okay, gripe over :>)


At any rate, you might be wondering what my plans are for the “miscellaneous” expense category? Well, here’s where I’ll solicit your help. There are a few items on my list that I need to do and others that I’d like to do. How I will (or will not) attain such will be up to you. In the near future (9 months), I’d like to (in decreasing order of expense amount):

  1. Max out my Roth IRA ($3,883.75 remaining)
  2. Pay for a trip to the Caribbean to celebrate my girlfriend’s birthday ($500)
  3. Set aside money for my boyfriend’s birthday ($300)
  4. Buy new clothes ($250)
  5. Vehicle window tinting ($200-$250), and
  6. Repair the crack in my windshield (I’m guessing $100-$200). 
Sometimes we can get everything we want, but rarely is that the case when you try to stick to the idea of “living within your means.” So, to get [all or some of] these things, I need your help to make some decisions and compromises. I will not use credit to purchase these items (clearly, this is one way to have it all, but I assure you that it’s quite costly) and I'm working within a fixed income (no overtime or part-time job here). Instead, I'll have to make some sacrifices. 


Let’s get started....
What need and want should I start saving for? Please select one of each and post your recommendation in the comment section. Thanks =)