Showing posts with label wants. Show all posts

Thursday, April 7, 2011

Tax Realities....Better Than I Thought

Several weeks ago, I lamented that my goal of paying off my car by the end of this month had been dashed. Why? Because I anticipated a $2500 tax return (federal and state) which would have have been applied to my loan balance....and then I started using TurboTax and I soon discovered that my refund, if any, would be no where near that. So I updated my debt repayment plan to reflect NO tax refund. After having a CPA friend help me sort through taxes for two states (and one municipality) I've learned that I do get a refund (federal and state; I actually owe in one state). Now I am wondering how I should spend my refund. I've already purchased $100 worth of savings bonds using IRS Form 8888, so I have roughly $1100 left to play with. If I apply all of it to the car loan, I can finish the note approximately 1 month early. I could also contribute the amount to my Roth IRA for the 2010, for which I have $3,670.89 remaining. I could spend a portion of it for two weddings (within the month). I could put it in my emergency savings account towards my $10K goal. Or, I could equally divide it among the abovementioned expenses/savings. Decisions, decisions, decisions.....


What would you do if you expected something, then didn't expect anything, yet received something? Would you stick to your original idea when you were expecting something or change course?

Tuesday, March 15, 2011

Thank Goodness I'm Out of School!

If, like school, my attendance was recorded on this blog, I'd probably be failing. I haven't posted in two weeks! Which is especially terrible since I post twice a week. Nevertheless, I will share what I have been up to.....spending money recklessly and not so recklessly.

The reckless part comes into play because my financial decisions over the past two weeks have effectively set my car payoff date back by a month. A large part of this is because I spent $1,010.31 (I negotiated this down from the original quote) to get my tie-rod and rear struts replaced (this is the "not so reckless" part of my spending). The rest of my car payment money (and then some) was spent on spa services ($188), dinner ($55), hair supplies ($20 and change), airfare, eating out (including Dunkin Donuts), and a new pair of sneakers ($44), among other things. 

Why the splurge? Why the major deviation from "the plan"? Frankly, there's no excuse, yet, I found myself justifying expenses because it was my birthday. Yup. I turned 27 years old last week. And unlike previous birthday celebrations, I did not plan for this one. No trip out of town. No dinner with my beau. Nothing. It was quite depressing. I guess that saying about money not being able to buy you happiness is true....I sure made an attempt at it (enter sad face).
Image from murlocparliament.com

Now it's time to refocus and get back on track. No more emotional spending, no more failing to plan and trying to make up for it at the last minute.

Have you ever made emotional purchases? Splurged in an effort to "fill a hole?" What was the consequence?

Thursday, December 9, 2010

I Needed this LAST WEEK!


I'm rather disgusted with how I've spent my money the past several weeks. Thoughtless credit card charges...countless transactions for eating out...blatant disregard for my spending plan. I've got $10 to my name (excluding all savings - easily available and not). Am I happy about it? Absolutely not. Is it the end of the world? Again, no.

So what's next? Buckle down and pay off the credit card balance and remind myself - DAILY- of why I have a spending plan. Then, make a list of things to purchase and stick to it. This should help me achieve some sense of redemption, because reflecting on the past several weeks of spending is not inspiring!

Have you ever gotten "down in the dumps" about recent spending? What have you done to reduce the likelihood of repeating such regrettable spending?

Monday, October 25, 2010

7 Days and 1,604.85 Dollars Later...

Last week, I posted "Decisions, decisions, decisions..." to reflect the conundrum du jour: should I use my "extra" paycheck for a trip to Houston or do other stuff with it?

Well, it took me less than a week to blow through more than my "extra" check. Here's how I did it:
  • $717.73 for bills ($689.01 for my car payment and $28.72 to pay off my credit card balance)
  • $255.64 for "other" or miscellaneous expenses (stamps, airfare, brake lights (the DIY replacement of $6.35 is much less than the $29.99 the rotor-replacers wanted to charge...more on them, next), pet food, public transportation fare).
  • $250.10 (on a credit card) for an unexpected car repair.
    • I had my coupon ready to go for my oil change, but after a road test (something that I insisted be done because I've been hearing squeaking while braking), I was informed that my front brake rotors needed to be replaced. Unfortunately, they were worn down to the point that resurfacing them (a cheaper alternative to rotor replacement) was not a feasible alternative.
  • $197.63 for food (sadly, more than half of this was spent on eating out, including this little indulgence).
  • $71.43 for gasoline.
  • $60 for an ATM withdrawal ($49.72 was spent on a day trip to NYC - tolls and food- and state park admission for a "hiking" trip in a part of the Appalachian Mountain range. I spent another $6 as a tip for lunch that I didn't pay for.) Sadly, I can't account for the outstanding $4.28.
  • $39.53 for savings (I wanted to make the amount in my ING Direct account an even number. Lame. I know).
  • $12.79 for a bottle of vino (yes, liquor has it's own category in my spending plan). Don't judge me ;)
All said and done, I will have $34.26 left over from this "extra" check. None of which, I might add, went towards a trip to Houston. I should mention, however, that part of the airfare cost listed in the miscellaneous category includes a membership fee for Spirit Airline's "$9 Fare Club." This service, at approximately $60, will pay for itself over the purchase of two airline tickets (one down, one more to go) as I will receive special fares for being a member ($19 one way ticket to travel 900+ miles, anyone?)

I know this isn't the most impressive record of spending "fun" money, but tell me, WHAT WOULD YOU HAVE DONE?

I guess I don't have "money to blow".....

 
From Candy Slice Comedy

Thursday, October 21, 2010

Why Aren't People Planning?

Have you ever had a financial premonition and were scared poopless? What were the circumstances and how did you deal with it?

I had such a moment when I participated in Dave Ramsey’s Financial Peace University at a local church (the first of 13 sessions). There were about 20-30 people in attendance, quite a few couples and only a handful of folks under the age of 30. We were asked to share our names and why we decided to attend. Stories poured forth about middle-aged individuals coming to the sudden realization that they had to find a way to pay for their 17 year old’s college education, prepare for a dignified retirement or dig out of mounds of consumer debt. In those moments, I thought to myself that there is no way that I would want to be in a similar conundrum. What’s more, these folks could have been in better [financial] circumstances if they had done one thing: plan. I recognize that recent market activity has wrecked havoc on retirement accounts, savings and other investments (I hear my family discuss how such activity has impacted their plans). I am not naive to the reality that folks have been losing jobs, either. In fact, my godmother has been through a few temporary employment stints in the past two years and she still hasn’t procured a permanent position.

I contend, however, that the individuals who planned (and executed their plans) fared better than those who did not plan (and execute) at all. Sadly, my observation about the company I was in during this class was that most of them failed to plan, altogether. Further, I find myself frustrated with individuals who find themselves in the "sudden" predicament of having to make a big purchase....and they haven't prepared for it.....and they're still spending money on random things (oh yeah! we just decided to go to Atlantic City this weekend to gamble and go shopping). So this forces me to ponder, how much time do people think they need to prepare for major expenses and how much time do they actually need to prepare for such expenses? Major  expenses = buying a home, paying for college, preparing for retirement, eliminating debt, etc. From my perspective, there are many people who are slacking on the finances, however, I could be overreacting. ..like this dude:


What do you think?

Thursday, October 14, 2010

I Like My Sweets Cheap

This post is about me being a glutton or a cheapo. Or maybe I'm a gluttonous cheapo. You be the judge...

I am a fan of Dunkin' Donuts Marble Frosted donuts. It doesn't help that there's a DD (this is what I call it in my expense tracker/budget) within 100 steps of my office. There have been a number of days when, right before work, I would make a pit stop to DD for a small hot coffee and one of my chocolate-drizzled-over-vanilla goodies. And on such days, I would spend $0.89 for a doughnut. Recently, I learned that if I purchase later in the day (say, after 3PM), I can get not one, but TWO doughnuts for the delicious price of $1! Now I know I'm spending $0.11 more than originally planned, and it's not like doughnuts are a healthy food choice, but gosh-darn-it, it feels good to know I can spend less (per doughnut) than necessary. Armed with this new information, I am less likely to get my sweet treat earlier in the morning when a premium is placed on the price. Instead, if I "have" to have a doughnut, I'll let the clock tick-tock away before I indulge (if I'm still thinking about something so relatively insignificant, I might as well get it, right?). Some of you may contend that  3PM doughnuts are, well, old. And cruddy, and no good, and stale and blah blah blah. Well, out of the many discounted doughnuts I've consumed, I can say that I've only had one that wasn't up to par. Aside from that, I've been getting my sweet-treats cheaply!

What items do you wait to purchase? 
Are you the person with all of the Halloween candy in the middle of November? Do you "forget" to go holiday shopping until after January 1?
What's worth it to you to wait to spend less?

Tuesday, October 12, 2010

Update: Roth, Car and Wants

To date, I've fretted about Roth contributions, using savings to keep up with $1k+ car payments and a list of wants. Well, here's a brief update:
  • Roth: I have not made any changes to my budget to redirect funds to my Roth account. So far, I'm saying "screw it." I'll be able to satisfy the $5,000 maximum contribution for 2011.
  • Savings for Car Payment: You have likely read that I placed myself in the possible predicament of using my savings to pay my car note because I used a substantial portion of car payment money to pay off my credit card. Well, I haven't moved any money from savings (my ING balance is around $1200) and my credit card still has no balance. As previously reported, my balance for the car note is just north of $8,000.
  • My wants: In the "It's My Budget! Part 3 of 3" post, I listed the following wants and needs: max out my Roth IRA ($3,883.75 remaining); pay for a trip to the Caribbean to celebrate my girlfriend’s birthday ($500); set aside money for my boyfriend’s birthday ($300), buy new clothes ($250); vehicle window tinting ($200-$250); and repair the crack in my windshield (I’m guessing $100-$200). Well, you already know about the Roth... I'm diligently saving for my girlfriend's birthday celebration in January (approximately $200/month)... I'm quite a bit unsure about what exactly I'm going to do for my boyfriend's birthday; whatever it is, I have to be realistic about it and make sure I plan for it :) Purchasing new clothes doesn't have to be a bulk purchase type of thing. Recently, I went to a discount clothing store and purchased a few items (I spent $37.07). The money came from the $66.80 reimbursement I received from work... I can postpone the window tinting. I'm likely to get it done for a much cheaper price if I looked outside the metro area that I live in... And the crack in my windshield? I got a quote for $114.95 + taxes. Now I just have to find the time to get it fixed!
What are your thoughts? Would you do the same thing if you were in my shoes?

Tuesday, October 5, 2010

A Little Extra Something...

I got a check, I got a check, I got a check, hey hey hey hey! I received a reimbursement check from my job and I don’t know what to do with it. By no means is it a tremendous amount- it’s a modest $66.80- but I’m still scratching my head as to what I should do with it. Normally, I apply such checks to my credit card balance. But I don’t have a credit card balance (yippee!). I could blow the money on something beauty-related (like this maybe?). Go out to eat. Put it in my savings account. Put it in my Roth or brokerage account. Give it away. Or let it sit in my checking account just for the sake of it.

What do YOU think I should do with my $66.80?

Tuesday, September 21, 2010

It's My Budget! Part 3 of 3

In the last two posts, I shared my budget and categories of spending that were non-negotiable and maybe negotiable. Today we will cover the part of my budget where I have the most flexibility/options. 


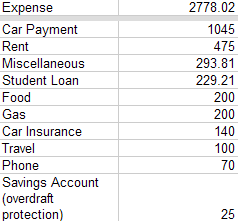
Every month, I will spend $293.81 for my most negotiable spending category: Miscellaneous!
The amount available for miscellaneous expenses has increased by $200 recently because of a change in my car payment ($1245 to $1045). What exactly qualifies as “miscellaneous”? Pet expenses (I have two furry friends** that require food and litter), storage rental (I’m hoping to lose this expense SOON; a little more about this later), entertainment, gifts, airfare to see my sweetheart and occasional car maintenance (think oil changes and car wash). **I wish my cats were as cool as these two...


Although I like to think that my budget in reality reflects exactly what’s on this spreadsheet, the sad truth is that I occasionally use my credit card to make purchases.....and I often don’t pay the balance in full every month (YIKES!) What’s not-so-sexy about this idea is that I know interest charges are lost opportunity costs. Having looked at my credit card statements for the past 8 billing cycles (starting since January 11, 2010), I’ve paid $59.11 in credit card interest. That’s enough money to fill up my gas tank and buy a decent lunch! Fortunately, the miscellaneous category of expenses also includes me taking a stab at whatever credit card balance exists, so it’s not an ever-growing ball of debt.


Now about that storage unit...
I’m working on getting a nice chunk of money from selling all of what I have (it’s mostly furniture), but I am more excited at the prospect of reclaiming $97 a month (bye-bye monthly storage payment; hello more money for saving, expenses, credit card balance elimination, etc.!). I’ve posted items for sale on Craigslist and received a few responses, but none that adhere to the requests of the post (Hey Craigslist customers! Please read the entire post before you start emailing sellers silly questions about what’s for sale. The information is already there! Okay, gripe over :>)


At any rate, you might be wondering what my plans are for the “miscellaneous” expense category? Well, here’s where I’ll solicit your help. There are a few items on my list that I need to do and others that I’d like to do. How I will (or will not) attain such will be up to you. In the near future (9 months), I’d like to (in decreasing order of expense amount):

  1. Max out my Roth IRA ($3,883.75 remaining)
  2. Pay for a trip to the Caribbean to celebrate my girlfriend’s birthday ($500)
  3. Set aside money for my boyfriend’s birthday ($300)
  4. Buy new clothes ($250)
  5. Vehicle window tinting ($200-$250), and
  6. Repair the crack in my windshield (I’m guessing $100-$200). 
Sometimes we can get everything we want, but rarely is that the case when you try to stick to the idea of “living within your means.” So, to get [all or some of] these things, I need your help to make some decisions and compromises. I will not use credit to purchase these items (clearly, this is one way to have it all, but I assure you that it’s quite costly) and I'm working within a fixed income (no overtime or part-time job here). Instead, I'll have to make some sacrifices. 


Let’s get started....
What need and want should I start saving for? Please select one of each and post your recommendation in the comment section. Thanks =)